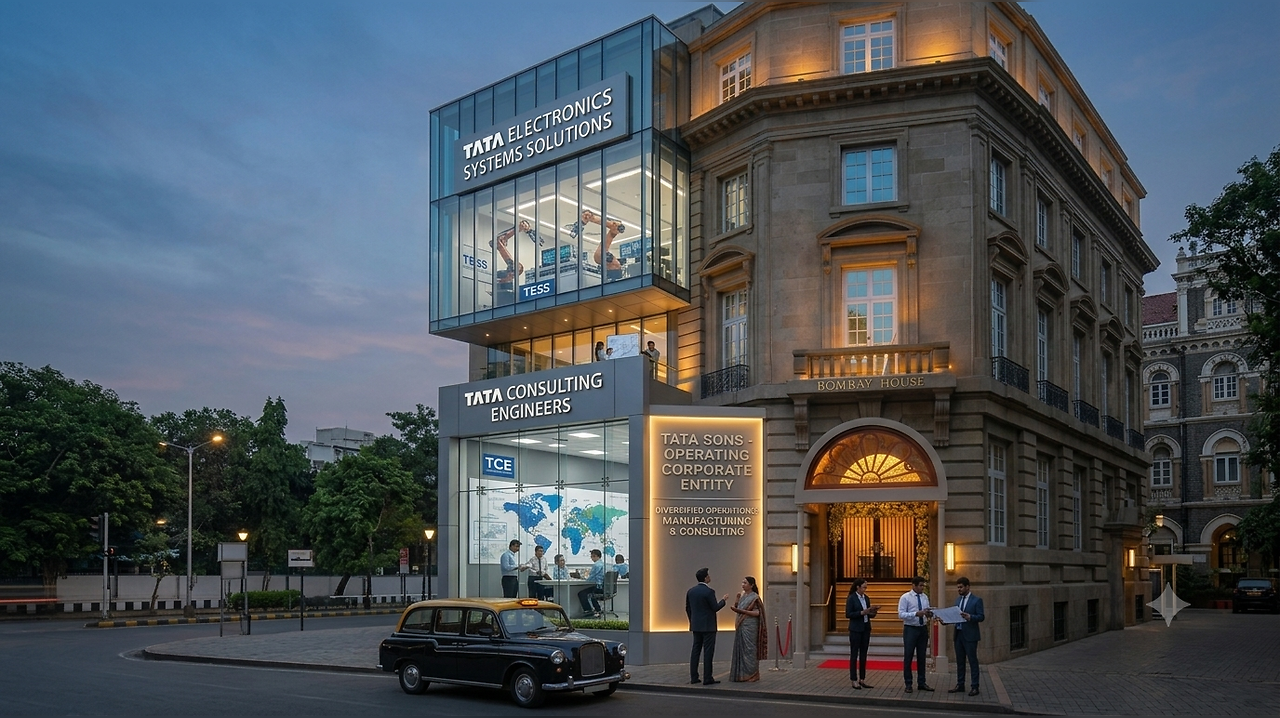
Tata Trusts’ proposal to merge Tata Electronics Systems Solutions Private Limited (TESS) and Tata Consulting Engineers (TCE) into Tata Sons could alter the regulatory character of the group’s principal holding company. The proposed restructuring could potentially shift Tata Sons from a predominantly financial and investment holding entity towards an operating corporate structure.
Experts say this change could have implications for its classification as a Non-Banking Financial Company (NBFC) or Core Investment Company (CIC), and consequently for the listing requirement linked to that regulatory framework.
T. V. Mohandas Pai, Chairman of Aarin Capital Partners, said the proposed restructuring could help Tata Sons change the composition of its income by bringing manufacturing and consulting revenues into the holding company.
“The recent suggestion of Tata trusts to merge 2 large operating cos into Tata sons is an interesting strategy to get over the RBi requirements of a listing for large NBFC’s. The result will be that the operating income of Tata sons will be largely from manufacturing and consulting than from financial income and dividends. The basic requirement of a NBFC is that majority of income comes from interests, dividend or financial services,” he said.
Pai added, “Technically Tata sons then will cease to be a NBFC. This may avoid the listing requirements. A way out of the current dilemma.”
Ajay Bagga, a financial market expert, also described the proposal as an attempt to change the regulatory nature of Tata Sons, while stressing that the implications could extend beyond compliance.
“The proposed merger of Tata Electronics Systems Solutions (TESS) and Tata Consulting Engineers (TCE) into Tata Sons is a strategic attempt to reclassify Tata Sons as an operating company rather than a financial holding entity, potentially allowing it to shed its RBI-mandated NBFC/CIC status and avoid compulsory listing. If approved, this move could materially alter Tata Sons’ regulatory character, capital allocation flexibility, and governance dynamics,” he said.
Why Experts Are Focusing On Tata Sons’ Regulatory Status
The proposed merger is major because the regulatory treatment of an operating company differs from that of an entity falling within the applicable NBFC or CIC framework.
H.P. Ranina, Advocate, Supreme Court of India and corporate lawyer, said the restructuring will change Tata Sons from primarily an investment and financial holding company into an operating corporate entity.
According to Ranina, the RBI’s regulatory powers in this area arise from its mandate under the RBI Act, 1934, particularly in relation to entities covered by the applicable NBFC and CIC framework.
He noted that an ordinary operating company is not regulated by the RBI in the same manner as an NBFC or Core Investment Company.
Therefore, if the proposed merger results in Tata Sons becoming an operating company rather than a predominantly financial or investment company, and the resulting structure falls outside the relevant RBI framework, the listing requirement arising from that framework may potentially no longer apply.
Ranina said that if the proposed merger goes through and the resulting structure is no longer covered by the relevant RBI regulations, Tata Sons could potentially remain outside the RBI’s regulatory requirement for listing.
Tata Trusts Plan To Bring Two Operating Companies Into Tata Sons
Tata Trusts, which hold a 66 per cent stake in Tata Sons Private Limited (TSPL), have proposed merging TESS and TCE with TSPL.
The Trusts have asked the TSPL Board to examine and approve the proposal and initiate the regulatory process required to implement the transaction.
The proposed restructuring would increase the operating component within Tata Sons and bring substantial business revenues directly into the holding company.
The Trusts have said that this would restore an operating model that Tata Sons followed for much of its history. For nearly eight decades of its 100-year existence, TSPL had operating businesses and generated operating revenues, which also helped finance newer ventures within the Tata Group.
Tata Consultancy Services (TCS), for instance, operated as a division of TSPL before it was demerged into a separate subsidiary in 2004.
Ajay Bagga pointed to the same historical precedent.
“The restructuring reverts Tata Sons to its historical model as both an operating and holding company, similar to its pre-2004 structure when TCS was housed within Tata Sons.”
Operating Revenue Could Change Tata Sons’ NBFC Classification
The financial composition of the proposed combined entity is central to the regulatory argument.
According to figures provided by Tata Trusts, the amalgamated entity would have operating revenues of Rs 105,043 crore as of March 31, 2026. Income from financial assets stood at Rs 40,072 crore.
Operating revenues would account for 64.3 per cent of the combined entity’s total income.
Based on these figures, Tata Trusts said the reorganised TSPL would not meet the “principal business criteria” required for classification as an NBFC.
This is also the key point highlighted by Pai. With manufacturing and consulting operations contributing a larger share of income, Tata Sons’ profile could shift away from one dominated by financial income and dividends.
If the resulting entity no longer satisfies the relevant NBFC criteria, the regulatory obligations associated with that classification would need to be reassessed.
Tata Sons’ CIC Status Could Also Be Affected
The proposed restructuring could also change Tata Sons’ position under the Core Investment Company framework.
Tata Trusts said the resultant entity would have aggregate net assets of Rs 200,158 crore as of March 31, 2026. Investments in Group Companies would account for Rs 177,120 crore.
According to the Trusts, these investments would represent less than 90 per cent of the resultant entity’s aggregate net assets. Consequently, the reorganised Tata Sons would not meet the applicable criteria for classification as a CIC.
If Tata Sons ceases to qualify as a CIC following the restructuring, it would also need to surrender its existing certificate of registration.
Capital Allocation And Governance Questions
While the potential regulatory impact is a major element of the proposal, Bagga said the restructuring also needs to be examined in terms of how Tata Sons manages its investments and capital.
“One issue deserves particular attention: Tata Sons is not simply a conventional holding company. Its investment portfolio, including its substantial stake in TCS, represents a significant source of financial flexibility. The merger would therefore need to be assessed not only for its regulatory impact, but also for how it changes the allocation of capital, the risk profile of the parent and the relationship between the parent and its operating subsidiaries,” he said.
The observation highlights that a change in Tata Sons’ regulatory classification could have consequences beyond whether the company remains subject to a particular listing requirement.
The resulting structure could also affect how capital moves between the parent and its operating businesses, how the parent’s investment portfolio is managed and how its relationship with group companies evolves.
RBI Approval Is Still Required For The Proposed Merger
The restructuring would not automatically take Tata Sons outside the RBI framework. The merger of operating, non-financial companies with an NBFC would have to comply with the Reserve Bank of India (Non-Banking Financial Companies – Voluntary Amalgamation) Directions, 2025.
The framework requires a prior ‘no objection certificate’ from the RBI for the proposed transaction.
Tata Trusts have said they, along with TSPL, would engage with the central bank on all aspects of the proposed reorganisation. The Trusts have also asked the TSPL Board to take the necessary steps, including approaching the RBI for the required approval.
The final regulatory position would therefore depend on the proposed merger receiving the necessary approvals and the resulting entity being assessed under the applicable framework.
Tata Trusts Want Tata Sons To Remain Unlisted
The proposal also comes against the backdrop of the Tata Trusts’ stated objective of ensuring that Tata Sons continues as an unlisted private company.
The Trusts said the Boards of the Sir Dorabji Tata Trust and Sir Ratan Tata Trust had unanimously passed resolutions in July 2025 calling for efforts to ensure that TSPL remains an unlisted private company.
The proposed restructuring could therefore become an important part of the group’s approach to addressing Tata Sons’ regulatory classification while retaining its unlisted structure.
For Tata Sons, the proposed merger would bring two operating businesses directly into the holding company and increase the contribution of operating revenues. For the experts, the significance lies in what that change could mean for the company’s NBFC/CIC status, RBI-linked listing requirements, capital allocation and governance.
The proposal, however, remains subject to the regulatory process, including consideration and approval by the RBI.
